Many companies use the end of the year or first of the new year to do merit raises or cost of living adjustments which means more money in your paycheck! But what happens to that extra money in your paycheck? If you don’t make a plan to give your money a job, then often it just ends up being spent from your checking account. Here are 6 ways to use a raise to accelerate your wealth!
If you have not received a raise recently, then your paycheck is not buying as much as it used to! It is time to go ask for one! All the tips you need to know are here!
If you use a raise to accelerate your wealth, you can painlessly increase your debt repayment or savings rate without changing your take-home pay. You continue living on the same monthly income, but you now are generating wealth with an extra several hundred or thousand dollars each year without even noticing the impact!
As you advance with your career some raises will be larger merit or promotion raises, and others will be the smaller cost of living type raises.
For the smaller cost of living raises (2-3%), I will put the entire amount towards one of these wealth-building goals. For the larger merit or promotion raises (5-10%), I will usually put about half of the raise towards these wealth-building goals, and then treat myself or have a little “lifestyle inflation” with the rest.
You want to give yourself a mental reward for all of the savings you are doing so you can enjoy the life you are living right now too!
How much is your raise?
The first thing you need to know is approximately how much your raise is per paycheck. Raises usually are given either as a percentage (%) increase or a dollar amount increase per hour or per year.
If you received a percentage raise, then take the gross amount of an average paycheck and multiply it by the percentage increase. This is how much more you will receive each paycheck. As an example, if your paycheck is usually $1,500 every two weeks, and you receive a 3% raise, your paycheck will increase by $45 each paycheck.
If you received a dollar raise, then calculate the raise a couple of different ways. One easy option is to use the average hours per paycheck multiplied by your raise. If you received a $0.50 raise, and work 80 hours in a 2 week pay period, then your raise would be $40 each paycheck.
If your raise was an annual lump sum, then divide the total by the number of paychecks you receive each year (52 if you are paid weekly, 26 if you are paid every 2 weeks, 24 if you are paid twice a month, and 12 if you are paid once a month). So a $2,000 raise for someone paid every two weeks translates into $76.92 per paycheck.
Now that you know how much you have to work with, let’s give this extra money a job!
What are your current financial goals?
Take a few minutes to identify what your financial priorities are at this time. Are you focused on paying down debt, increasing your retirement contributions, saving for a goal (like travel or a car)? Ask yourself what is important to you right now.
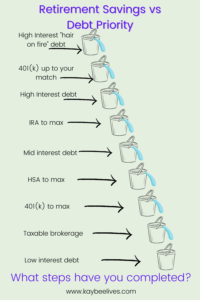
If you are not sure about what the next wealth generation step is for you, this saving/debt hierarchy may be helpful to determine where you are at and what the next step to take is.
If you have an idea of what you want to do with your raise, then make a plan, set up automatic transfers or payments, and put that new money to work generating wealth for you!
I have some common ideas listed below to get you started if you are not sure where to begin. All of these are good ideas to help you build your wealth and have a safety net. Consider what would work best for you and align with your goals, but don’t agonize or stress over these choices. They are all good choices, so pick one and make a plan to get started ASAP!
6 ways to use a raise to accelerate your wealth.
Increase your retirement contribution at work with part of your raise.
If you are already deferring a certain percent of each paycheck, then increase that by the same percentage as your raise, or by the extra dollar amount of your paycheck that you calculated above. If you have not yet started contributing to your workplace retirement plan, get on it! Often there is an employer match which is essentially free money for you! Find out how to sign up here!
Increase your automatic payments on your highest priority debt.
Add an extra payment each month or every 2 weeks depending on your paycheck schedule to pay off that debt faster! Once you pay off the highest debt, snowball that payment and any extra into your second priority debt and you will snowball your debt down to zero in no time!
Set up a high-yield savings account for something you want.
If there is a large ticket item you are wanting to purchase (examples could be a house, car, furniture, hobby item), then start an HYSA. Once it is open, automatically transfer the amount of your raise to this account with each paycheck. By doing this, you will be making regular contributions and staying motivated to meet your goal to make the big purchase!
Contribute to an IRA with each paycheck in addition to your work retirement contribution.
If you are not already contributing to an IRA account, then start one and send your raise amount into the account with each paycheck! The limit is $6,000 per year and the wealth that can come from maxing out this account for 30-40 years is astonishing! You can check it out here. If you do not have an IRA open, you can learn how to open one in this post. I recommend using Vanguard, Fidelity, or Schwab as reputable, low-cost, brokerage firms.
Start saving for your emergency fund or F-Fund.
Especially if you are single, having a funded emergency fund or F-Fund is critical for keeping yourself out of high-interest credit card debt if something unexpectedly changes in your life. If you do not have 3-6 months of expenses in a savings account as a safety net, then get started with this! Contribute monthly and make this account untouchable unless you have an emergency like a medical crisis, job loss, or surprise living situation change.

Make a plan to purchase something that will save you money in the long term.
Sometimes spending money now can save you money over the long term. These may be expenses like making your home design work better for you through a remodel. Or being more energy-efficient through an improved furnace, LED bulbs, or better insulation. Upgrading an older gas guzzler to a fuel-efficient car so you pay less in fuel, insurance, and repairs. Or buying cooking equipment to make cooking at home easier and more fun! An air fryer, quality pots, and pans, and a knife you are comfortable with can make a world of difference!
The Takeaways!
All of these options are good ones for stashing away money regularly to grow your wealth. The more you can save in your early working years, the longer it has to work and grow thanks to the magic of compound interest. So get started on saving for retirement and paying down debt early in your career!
You don’t have to wait until the new year to make changes like these! If you recently received a mid-year raise, or just have excess from your paycheck accumulating in your checking account, then you can set any of these up at any time!
So, as you start the new year, what are you going to do to use a raise to accelerate your wealth? I would love to hear and be encouraged in the comments or over on our Instagram page!
Pin Me!
These are excellent recommendations! I have definitely been thinking about what to do with my Christmas bonus and trying to fight the urge to just treat myself. And I really like the retirement savings/debt priority chart, it’s a good way to keep your focus. Thanks for the article!
Congratulations on the bonus! I absolutely think you should treat yourself with part of the bonus! Buy something you have your eye on! But balance that out with doing something like funding your IRA, or putting a lump sum into a savings account too!
One of my goals this year is to save enough money. And these are some great tips for me to do! Thank you very much for sharing your insights. x
I actually will be getting a raise In about a month! We talked about how it could really make an impact on my debt! Thanks so much for showing me the sign that I needed to use the extra to pay down my debt!
Yay! Setting up an automatic payment for an extra amount will make a big impact in your debt vs making the minimum payment! Congratulations on the raise!
Such a great post! It’s so important to know how to use and save money!
Yes! It is definitely an important tool for people as they navigate adulthood!
This is so helpful! My husband got his usual bonus in December, but he also received a surprise raise! I’m glad that I ran across your post. Thanks for sharing.
Yay! Surprise raises are always fun! I hope you can plan to put some of that to work and also have fun with part of it!
These tips to accelerate your wealth are great! I will share some of these tips with my friends. Thanks for sharing.
Yay! Thanks for looking out for your friends and not being afraid to talk about finances with them! Thanks for sharing!
Thank you for these great tips. All are great ideas. My husband is a big proponent of increasing the retirement fund contribution. I also like the idea of the high interest saving account.
These are good tips to maximize use of salary increase and make sure it is use properly.
This is an excellent idea.
Great ideas. I’m nearing the age to where I can’t utilize all the options but just saving the COLAs is a good idea.
Glad that you are doing well and every little bit helps! Thanks for the comment!
I am a big fan of paying off debt and I live your bucket illustration. Thanks for the clear explanations and tips about using a raise.
Great idea!